In the isolated-margin example used here, Bybit’s liquidation engine takes over a liquidated futures position using the bankruptcy price as its settlement reference. The difference between that reference and the eventual execution price can add to or draw from the insurance fund. It is not simply a fee paid to the exchange.
ADL is a separate risk mechanism. The applicable eight-hour drawdown or combined independent-pool balance condition can trigger it; a zero fund balance is not required in every case. Current pair-level parameters and the account’s margin mode take precedence over a general example.
This guide uses an illustrative isolated-margin example, not an account-specific quote. The Insurance Fund and ADL mechanism source review recorded below is dated October 23, 2026. Editorial update on October 26, 2026: introduction and navigation; this does not reset every factual verification date.
On this page
1. What is liquidation on Bybit?
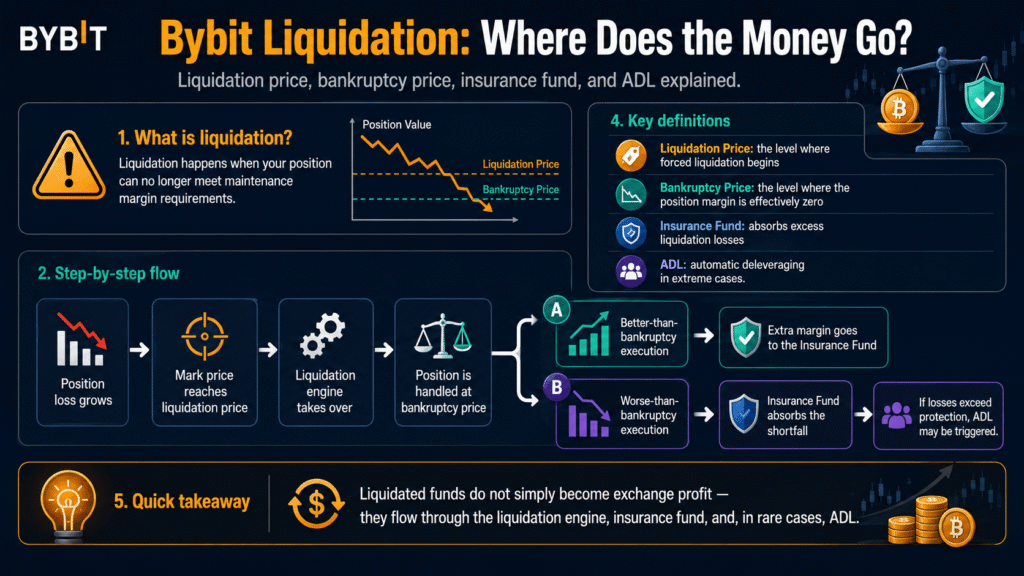
Liquidation is the process by which the system forcibly closes a position when the position’s losses grow to the point where the required maintenance margin can no longer be met.
In Bybit’s Isolated Margin, liquidation can occur when the Mark Price reaches the liquidation price. Bybit’s official help documentation explains that in UTA Isolated Margin, when the Mark Price reaches the liquidation price, the position is settled based on the bankruptcy price.
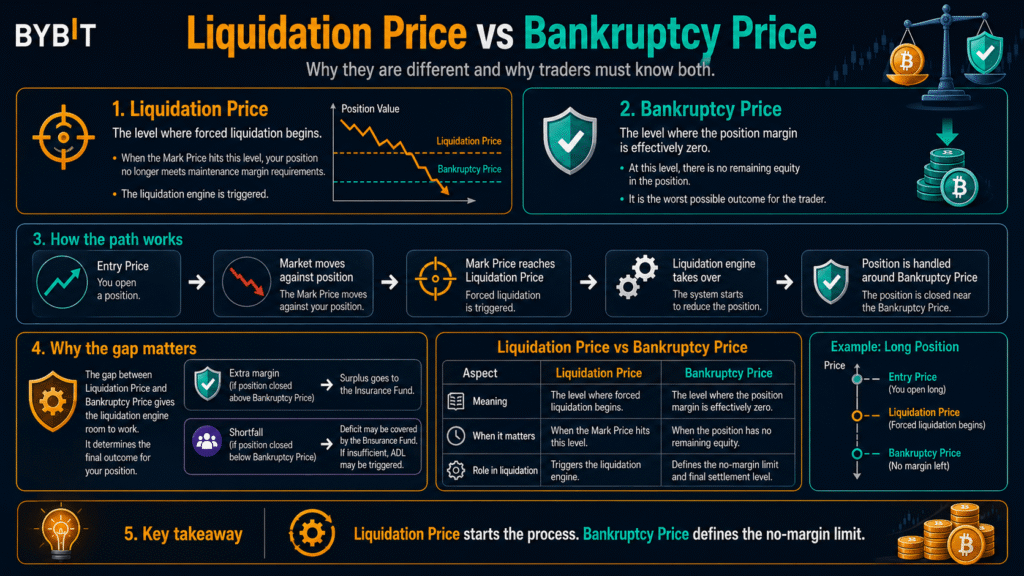
The liquidation price and the bankruptcy price are not the same. The liquidation price is the risk threshold at which the system begins to forcibly take over the position, while the bankruptcy price is the price at which the margin allocated to that position effectively becomes zero.
2. Difference between Liquidation Price and Bankruptcy Price
If you do not understand this difference, you may wonder, “My position was closed at the liquidation price, so why was there no remaining margin?”
Liquidation Price
The liquidation price is the price at which a position begins to be forcibly processed by Bybit’s liquidation system.
In isolated margin, the liquidation condition can be met the moment the Mark Price reaches the liquidation price.
Bankruptcy Price
The bankruptcy price is the price at which the position’s margin balance becomes zero and can no longer cover losses.
Bybit explains that when a liquidation occurs, the liquidation engine takes over the position and processes it based on the bankruptcy price, i.e., the takeover price.
Key Differences
| Category | Liquidation Price | Bankruptcy Price |
|---|---|---|
| Meaning | Threshold where forced liquidation begins | Price where position margin becomes zero |
| Role | Risk management trigger | Settlement basis for the liquidation system |
| Sequence | First | Subsequent settlement basis |
| Importance to user | Point of forced position closure | Determines loss/insurance fund structure after liquidation |
3. Does Bybit just take the liquidated money?
It is not that simple.
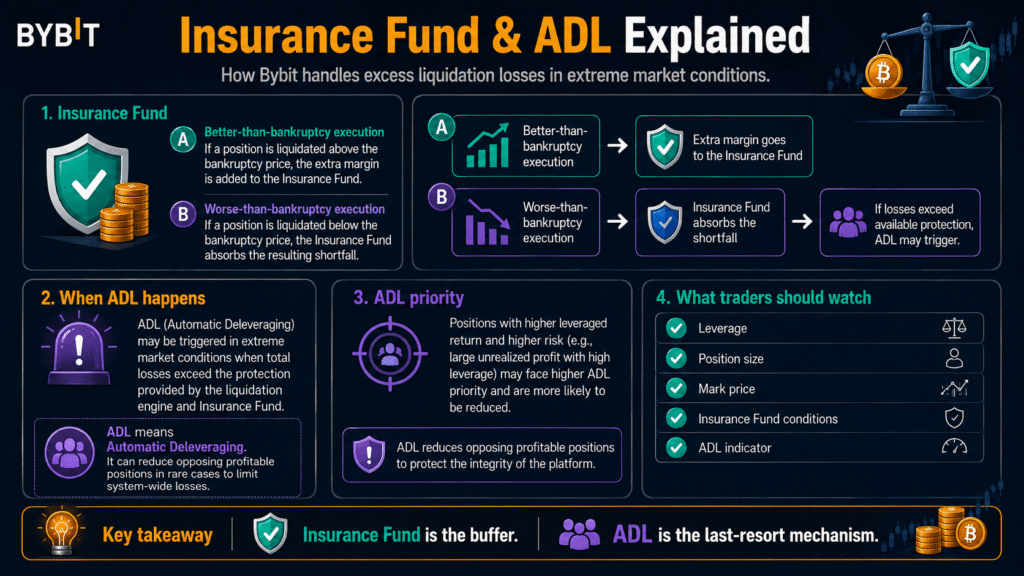
In Bybit’s futures/perpetual contract liquidation, after the liquidated position is taken over by the system based on the bankruptcy price, the difference that occurs when the position is actually settled in the market is linked to the insurance fund.
It is easy to understand by dividing this into two situations.
Situation A — Actual settlement price is more favorable than the bankruptcy price
If the liquidated position could be settled in the market at a better price than the bankruptcy price, a difference occurs.
This remaining margin goes into the insurance fund.
Situation B — Actual settlement price is less favorable than the bankruptcy price
Conversely, if the market moves too quickly and the position is settled at a worse price than the bankruptcy price, a situation may arise where the user’s initial margin is insufficient to cover the loss.
This excess loss is covered by the insurance fund.
Therefore, it is inaccurate to say that “the exchange takes all liquidated money as profit.”
4. Actual flow of liquidated funds
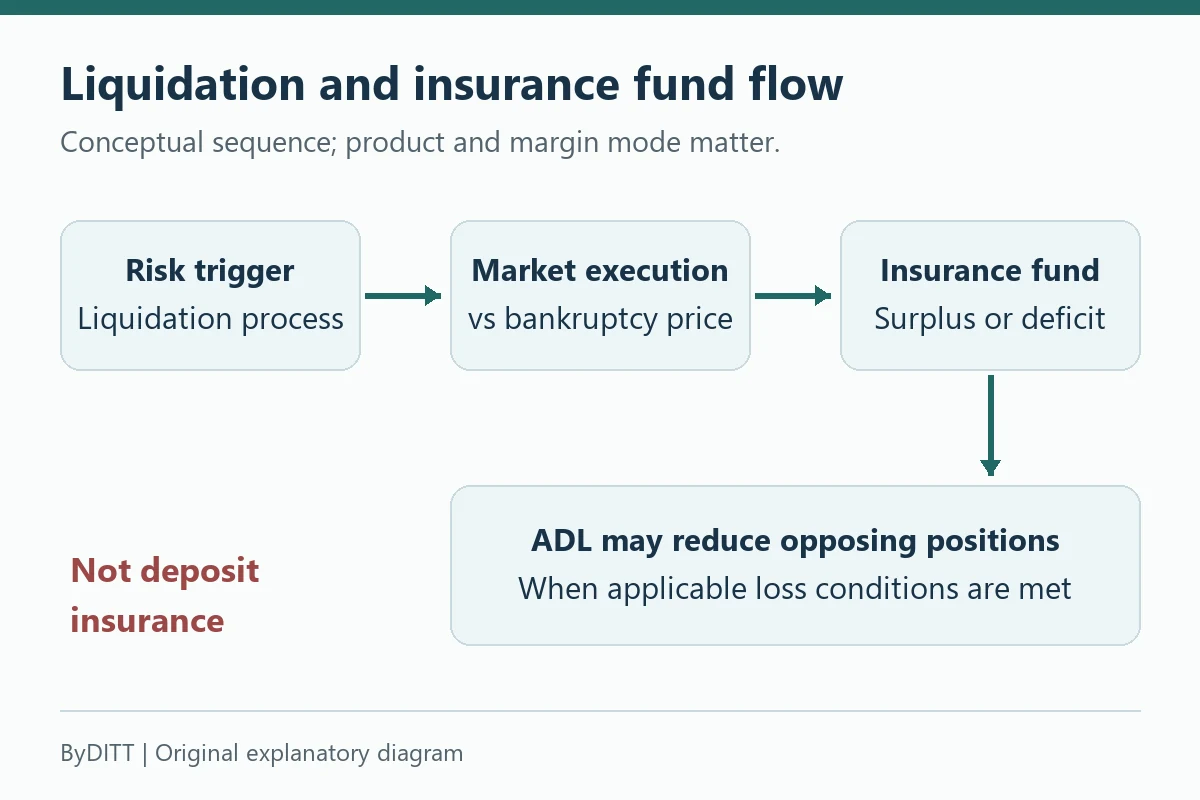
Simply put, the sequence is as follows:
User position loss increases
→ Liquidation price reached
→ Liquidation engine takes over position
→ Settlement based on bankruptcy price
→ Position closed in actual market
→ If more favorable than bankruptcy price, insurance fund increases
→ If less favorable than bankruptcy price, insurance fund decreases
→ ADL may apply if Bybit’s pair-specific eight-hour drawdown or combined independent-pool trigger is met
This is a conceptual flow, not a guaranteed sequence for every contract or account. Check the applicable margin mode, pool and pair parameters.
5. Liquidation structure seen through Bybit’s official example
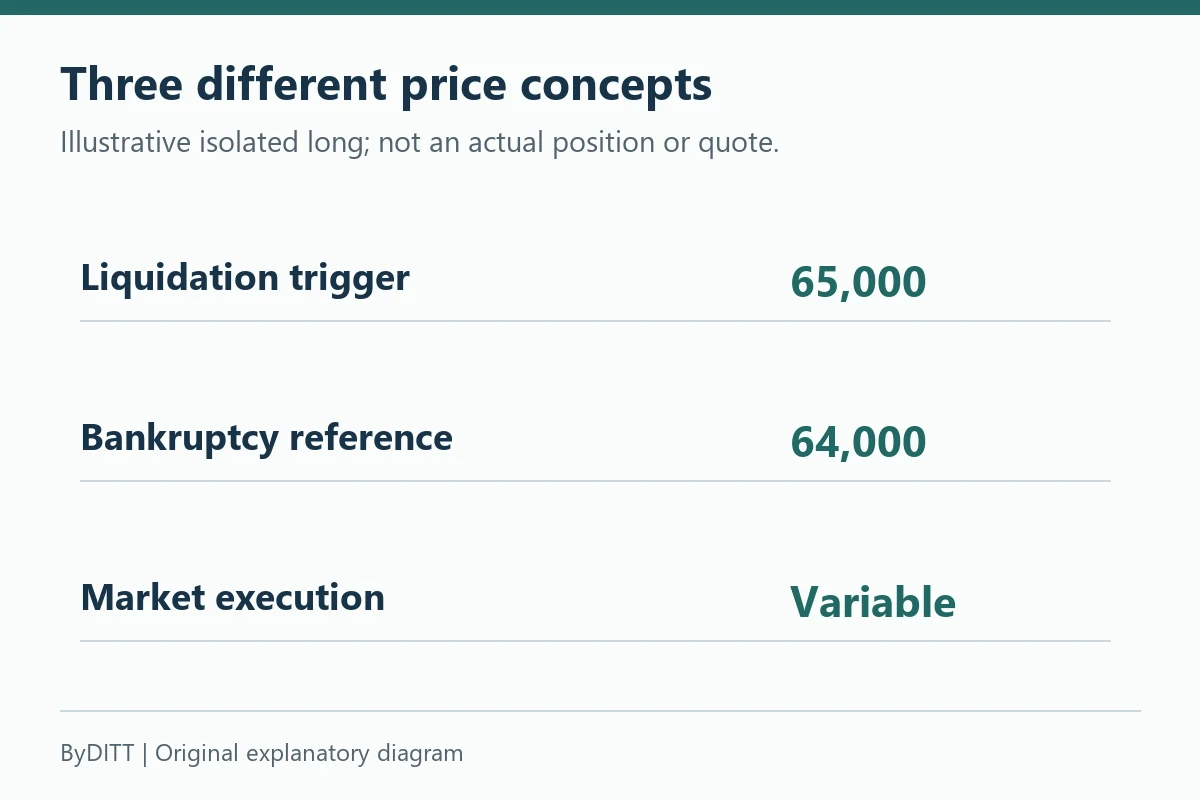
Bybit presents an example of the following structure in its official insurance fund explanation.
For example, assume there is a BTCUSDT long position.
- Liquidation Price: 65,000 USDT
- Bankruptcy Price: 64,000 USDT
When the Mark Price reaches 65,000 USDT, the position is liquidated. However, the system settlement basis is not 65,000 USDT, but the bankruptcy price of 64,000 USDT.
Afterward, if the position is settled in the actual market:
- If it could be settled at 64,980 USDT → More favorable than bankruptcy price
- If it was settled at 63,950 USDT → Less favorable than bankruptcy price
In the first case, the remaining difference goes into the insurance fund, and in the second case, the excess loss incurred below the bankruptcy price is covered by the insurance fund.
The prices are Bybit’s published illustrative example, not a live BTCUSDT quote; the actual amount also depends on position size and contract terms.
6. Why is the bankruptcy price less favorable than the liquidation price?
Taking a long position as an example, generally:
Entry Price > Liquidation Price > Bankruptcy Price
The reason is that when the liquidation price is reached, a very small amount of maintenance margin still remains.
Bybit forcibly separates the user from the position at the liquidation price, then hands the position over to the liquidation system based on the bankruptcy price.
In other words, if a user thinks, “The liquidation price is $65,000, so the loss is exactly confirmed at $65,000,” they have misunderstood the structure.
7. Why the bankruptcy price might not be visible on the candle chart
There is an important part in Bybit’s official explanation.
Because a liquidated position is not processed through the matching engine like a regular user’s order, but can be processed separately by the liquidation engine, the bankruptcy price itself may not be displayed on the chart candles.
Therefore:
“I looked at my chart and the price never went there, so why was it processed at the bankruptcy price?”
This question may arise.
The bankruptcy price is not a market execution price concept that must appear as is on a regular execution chart.
8. What is the Insurance Fund?
The Bybit insurance fund is a reserve fund intended to absorb excess losses occurring from liquidated positions.
The purpose of the insurance fund is twofold:
- Compensate for excess losses when a liquidated position is closed less favorably than the bankruptcy price
- Reduce the possibility of ADL occurring in extreme situations
Bybit describes the insurance fund as a risk buffer that reduces the direct transfer of excessive losses in futures trading to other traders.
9. Where does the money for the insurance fund come from?
One of the main sources of funds for the insurance fund is the difference that occurs when a liquidated position is settled at a better price than the bankruptcy price. Bybit also explains that its own contributions are a source of funding for the insurance fund.
For example:
- Bankruptcy Price: 64,000
- Actual Liquidation Execution Price: 64,500
If so, the liquidated position was settled in the market $500 more favorably than the bankruptcy price.
The excess margin generated in this process is credited to the insurance fund.
10. Whose money is the insurance fund?
The insurance fund is not a personal insurance account for a specific individual user.
It is closer to a collective risk reserve fund to manage liquidation risks for the entire platform or specific trading pairs.
Bybit explains that some trading pairs use a shared insurance fund pool, while others may use independent insurance fund pools depending on the project’s risk characteristics.
Therefore:
“Can I get back the money that went into the insurance fund when I was liquidated before?”
You might think so, but it is not that kind of personal savings structure.
11. Is it always safe if the insurance fund is large?
If the size of the insurance fund is large, the capacity to handle extreme liquidation losses may be greater.
However, that does not mean: “Since the insurance fund is large, my position will not be liquidated.” This is not what it means.
The insurance fund does not prevent a user’s liquidation; it is a system that handles the excess losses of a position after a liquidation has already occurred.
An individual user’s possibility of liquidation is affected by:
- Leverage
- Margin
- Entry Price
- Position Size
- Mark Price
- Margin Mode
- Maintenance Margin
and so on.
12. What happens if the insurance fund is insufficient?
ADL can become relevant in extreme liquidation events, but a depleted fund is not the only published trigger. Bybit describes a pair-specific eight-hour insurance-fund drawdown threshold and, separately, a combined balance of multiple independent pools at or below zero. The pair’s current trigger and stop parameters should be checked in Bybit’s ADL information.
According to Bybit’s official help documentation, in extreme market situations where the insurance fund alone cannot cover liquidation losses, the ADL system automatically reduces a portion of the counterparty’s position to handle the overall system risk.
To express this simply:
Liquidated position → bankruptcy-price reference → market close → insurance-fund credit or debit. Separately, if an applicable ADL trigger is met, opposing positions may be reduced under Bybit’s ADL ranking rules.
13. What is ADL?
ADL (Auto-Deleveraging) can automatically reduce ranked opposing positions when Bybit’s published trigger conditions are met. Profitable or highly leveraged positions are generally prioritized, but the official rules also state that an opposing position at a loss may be selected. ADL is not synonymous with an individual position’s liquidation.
For example, assume that large long positions were liquidated en masse due to a sudden crash.
If an applicable ADL trigger is met, Bybit may select high-ranked accounts among the opposite short positions; the ADL ranking is not a forecast of when the trigger will occur.
The selected positions may be automatically reduced in part or in full.
14. Is ADL the same as liquidation?
No.
Liquidation
Your position is forcibly closed because it is experiencing significant losses and cannot meet the maintenance margin.
ADL
Your position may actually be in profit or in a high-leverage state, but the system forcibly reduces some positions to handle large liquidation losses on the other side.
| Category | Liquidation | ADL |
|---|---|---|
| Cause | My position loss | Large-scale liquidation on the other side |
| Target | Risk position | Ranked opposing position; profitable positions receive priority, but a losing position is not categorically excluded |
| Purpose | Remove individual account risk | Handle system-wide losses |
| Insurance Fund Relationship | Insurance fund can be used | Subject to applicable pair-specific drawdown or combined independent-pool trigger |
| Frequency | Relatively common | Extreme market situations |
15. Who gets hit by ADL first?
Bybit explains that ADL ranking is determined based on leveraged return, i.e., return on investment reflecting leverage. Generally, the higher the return and the higher the leverage, the higher the ADL ranking can be.
On the Bybit trading screen, you can check your relative ADL risk through an indicator that shows ADL priority.
In other words, just because you are making a large profit with shorts during a market crash does not mean you are completely unrelated to system risk.
16. Does this mean that positions in profit can also be forcibly closed?
Yes.
For example:
- BTC crash
- Large-scale long position chain liquidation
- Rapid execution below liquidation price
- Large-scale depletion of insurance fund
- Loss cannot be handled by insurance fund alone
If this situation occurs, accounts with high ADL priority among short positions that were making large profits on the other side may be automatically reduced.
Therefore, ADL is a completely different type of risk from “forced liquidation due to losses” from the user’s perspective.
17. At what price is it settled when ADL occurs?
According to Bybit’s official explanation, the opposite position selected for ADL can be matched and settled based on the bankruptcy price defined by the insurance fund system.
Because of this, a difference may occur between the actual current market price and the ADL settlement price.
And that difference can be linked back to the insurance fund structure.
18. Are orders also canceled when ADL occurs?
Bybit guides that for users selected for ADL, the relevant position may be automatically closed, active orders may be canceled, and they may receive an email notification.
Therefore, during large-scale market fluctuations:
“I definitely set a stop-loss order, but the order disappeared.”
If such a situation occurs, it is necessary to check the transaction history and whether ADL occurred.
19. How high is the possibility of ADL occurring?
In a normal market, ADL often does not proceed because the insurance fund absorbs liquidation excess losses.
ADL becomes important mainly in extreme conditions such as:
- Market crash/surge
- Lack of liquidity
- Chain liquidation of large-scale leveraged positions
- Rapid decrease in the insurance fund for a specific trading pair
Bybit also describes ADL as a risk management device for extreme situations where the insurance fund cannot handle excessive liquidation losses.
20. Does Bybit ADL in 2026 only work when the insurance fund is 0?
Not always.
The latest official Bybit ADL documentation for 2026 explains a more specific trigger structure.
For example, ADL may be triggered when the drawdown of a single trading pair over the past eight hours reaches or exceeds its 8H PnL Drawdown Trigger Line measured against the insurance fund’s highest balance in that period. Bybit’s 30% trigger and 25% stop figures are an example, not universal thresholds.
A situation where the combined insurance fund balance of multiple trading pairs using an independent insurance fund pool falls to 0 or below is also explained as one of the ADL conditions.
In other words: “ADL only when the insurance fund number is exactly 0” If you simplify it like this, you cannot accurately explain the current Bybit structure.
21. Is liquidation loss ultimately the profit of the counterparty trader?
Only partially.
In the derivatives market, the transaction itself is formed by the counter-structure of longs and shorts.
However, it is not a structure where all of a specific user’s margin is transferred as is to a specific counterparty user just because that user was liquidated.
The liquidation engine and the insurance fund intervene in the middle.
If a liquidated position is settled more favorably than the bankruptcy price, the profit goes into the insurance fund, and if it is settled less favorably, the insurance fund covers the shortfall.
22. Does all liquidated margin disappear?
In isolated margin, a position reaching the bankruptcy price means that the margin allocated to that position is effectively exhausted. Bybit defines the bankruptcy price as the price at which the margin balance becomes zero.
However, in the actual liquidation process, after the user hands the position over to the system at the liquidation price, the difference between the market processing price and the bankruptcy price is linked to the insurance fund.
Therefore, from a user’s perspective, you may lose the margin of that position upon liquidation, but it is incorrect to understand that the amount simply belongs to the exchange’s general profit in system accounting.
23. Does Bybit charge a separate futures liquidation fee?
According to the official 2026 Bybit fee guide, it is explicitly stated that no separate liquidation fee is charged for Perpetual and Futures trading.
This point is quite important.
In other words, the reason why money disappeared after futures liquidation:
“The exchange took all the liquidation fees.”
If you explain it like this, it is not accurate.
Products for which Bybit specifies a separate liquidation fee include Spot Margin, Crypto Loan, Options, etc., and Perpetual/Futures are classified separately.
24. Isn’t it settled at the market price immediately at the liquidation price?
From a user’s perspective, the position is closed when the liquidation price is reached, but the internal risk processing structure is different from a simple regular market order.
Bybit explains that the liquidation engine takes over the position at the bankruptcy price. Afterward, the insurance fund increases or decreases depending on the difference between the actual market execution price and the bankruptcy price.
Therefore:
Liquidation Price = Actual Market Sell/Buy Execution Price = Bankruptcy Price
It is wrong to view them all as the same.
25. Example: When a long position is liquidated
The following is a simple example for conceptual understanding.
- BTC Entry Price: 70,000 USDT
- Liquidation Price: 65,000 USDT
- Bankruptcy Price: 64,000 USDT
Due to a market crash, the Mark Price reaches 65,000 USDT.
Step 1
Position liquidation starts
Step 2
Liquidation engine takes over the position based on the bankruptcy price of 64,000 USDT
Step 3
Position settled in the actual market at 64,500 USDT
Step 4
Closed at a price $500 more favorable than 64,000
Step 5
That difference is reflected in the insurance fund
This is the basic principle by which the insurance fund increases.
26. Opposite example: When the market crashes too quickly
Assume the same conditions, but the market crashed very quickly.
- Bankruptcy Price: 64,000 USDT
- Actual Market Closing Price: 63,500 USDT
This time, it was settled $500 less favorably than the bankruptcy price.
The user’s initial margin alone cannot cover this additional loss.
In this case, the shortfall is covered by the insurance fund.
And if such situations are repeated on a large scale and the insurance fund’s losses grow, the ADL risk may increase.
27. Why is an insurance fund necessary?
If there were no insurance fund, problems would arise during large-scale market fluctuations.
For example, assume a long position was settled far below the bankruptcy price, resulting in an additional loss of -10,000 USDT.
That user has already exhausted all position margin.
Then someone must cover this shortfall.
Traditionally:
- Exchange
- Other participants
- Loss-sharing system
etc.
Bybit uses the Insurance Fund first to absorb excess losses.
28. The Impact of the Insurance Fund and ADL on Market Stability
The most important role of the Insurance Fund is that it acts as a buffer to prevent liquidation losses from being immediately passed on to other normal positions.
Looking at this step-by-step:
First Line of Defense
Margin of the user’s position
Second Line of Defense
Insurance Fund
Third Line of Defense
ADL
If the Insurance Fund is sufficient, excess losses are handled in the second stage, reducing the likelihood of reaching ADL.
29. Why Should You Check the ADL Indicator?
Bybit provides an indicator on the position screen that shows ADL priority.
You can understand that the higher the indicator, the relatively higher the possibility of being subject to ADL in extreme market conditions.
It is especially worth checking in the following situations:
- Using high leverage
- High unrealized profit
- Sudden market drops or spikes
- Increased chain liquidations of trading pairs
- Sharp decline in the Insurance Fund
30. Can ADL Be Completely Avoided?
It cannot be fully guaranteed.
This is because ADL is a system designed to handle extreme losses across the entire market.
However, there are factors that users can influence to lower their ADL priority.
Bybit explains that ADL ranking is based on leveraged return.
Therefore, generally:
- Reducing excessive leverage
- Realizing a portion of profitable positions
- Managing position size in extreme markets
etc., can help reduce ADL exposure as a result.
However, this should not be interpreted as an absolute “ADL prevention formula.”
31. Are Liquidation Losses the Same for Isolated and Cross Margin?
Structurally, they are different.
Isolated Margin
Isolated Margin separates the margin allocated to a position from other eligible account collateral.
However, manually adding margin or enabling Auto-Margin Replenishment (AMR) can move additional available UTA funds into that position and increase the amount exposed to loss. Check the position’s AMR setting and added-margin history; AMR does not guarantee that liquidation will be avoided. See Bybit’s AMR explanation and the UTA margin-mode guide.
Cross Margin
The account’s available margin is shared across multiple positions. Therefore, the loss of one position can affect the entire account collateral.
If you are a beginner, do not just look at:
“How much will I lose if liquidated?”
but first check which margin mode your account is in:
- Isolated
- Cross
- Portfolio
You must check which margin mode you are using.
32. Can the System Reduce Some Positions Before Liquidation?
Risk management processes may vary depending on Bybit’s account and contract types.
Especially in Cross/Portfolio Margin, the entire account maintenance margin structure has an impact, so it is difficult to explain all situations with just the fixed liquidation price of a single position.
On the other hand, in Isolated Margin, the liquidation price based on individual positions is displayed more intuitively.
Therefore, in actual trading, you should check the official liquidation calculation structure according to your UTA margin mode.
33. Can I Get Back Money That Was Liquidated?
If a standard forced liquidation has been processed normally, there is no structure to return the margin consumed by the liquidation.
In particular, the bankruptcy price means the level at which the position margin becomes zero.
However, if you believe there was a separate issue such as a trading error or system failure, checking with Bybit Customer Support based on the transaction history is a separate matter.
You must distinguish between normal liquidation caused by market fluctuations and system errors.
34. “Doesn’t Bybit Make Money Since It Went to the Insurance Fund?”
Treating funds in the Insurance Fund as simple general operating revenue distorts the structure.
The Insurance Fund is a risk reserve used to cover excess losses when other liquidated positions are settled at prices worse than the bankruptcy price.
In other words:
Insurance Fund increases in favorable liquidations
Insurance Fund decreases in unfavorable liquidations
This repeats.
The Insurance Fund is not a structure that only accumulates unilaterally.
35. Can I Also Check the Bybit Insurance Fund Balance?
Yes, you can.
Bybit discloses Insurance Fund data on the Insurance History page, and explains that some insurance pool data can also be accessed via API.
The data structure may vary depending on whether a specific trading pair uses an independent Insurance Fund pool or shares it with other trading pairs.
This transparency can serve as a reference when understanding ADL risks.
36. If the Insurance Fund Is Decreasing, Does It Mean ADL Will Happen Soon?
Not necessarily.
A decrease in the Insurance Fund may be a signal that it is covering excess losses from liquidated positions, but ADL operates according to Bybit’s specific trigger conditions.
Therefore, simply judging that:
Insurance Fund decrease = ADL soon
is an oversimplification.
However, it is true that if the Insurance Fund is being depleted rapidly in an extreme market, it is worth checking the ADL risk.
37. If I Stop Loss Before Liquidation, Is It Unrelated to the Insurance Fund?
Generally, if a user closes a position manually in the market, it does not proceed to the forced liquidation process.
Therefore:
- Normal stop loss
- Market order close
- Limit order close
are different from forced liquidation where the liquidation engine intervenes.
The Insurance Fund, bankruptcy price, and ADL structure are important mainly when forced liquidation occurs.
38. Why Is It Better to Set a Stop Loss Price Before the Liquidation Price?
When liquidation occurs, the user loses control over the price and timing.
A stop-loss order lets the user specify a trigger and an intended exit method, not a guaranteed execution price or a fixed maximum loss.
For example, in a long position:
- Entry Price: 100,000
- Stop-Loss Trigger (illustration): 95,000
- Liquidation Price: 90,000
In this illustration, 95,000 is the stop-loss trigger, not a promised fill price. A triggered market order executes against available liquidity and may fill at a worse price; a triggered limit order may remain unfilled. If Mark Price reaches the liquidation threshold before the stop-loss exit completes, liquidation can occur first.
The 90,000 liquidation level is also an assumed example, not a live quotation or a value calculated from the 100,000 entry alone. Actual liquidation depends on the contract, position size, margin mode, added margin, maintenance-margin tier and applicable fees. A stop-loss setting does not override the liquidation rules.
Independent calculation, not an execution promise: assume a 1 BTC linear USDT position entered at 100,000 USDT, with no partial fills, fees or funding.
A completed exit at 95,000 gives price P&L = 1 × (95,000 – 100,000) = -5,000 USDT. If the actual exit instead completes at 94,000, price P&L is -6,000 USDT.
These are two assumed fill outcomes, not a maximum-loss range. Actual fees, funding, partial fills and margin additions must be reconciled separately.
Scope checked October 25, 2026: see Bybit’s TP/SL instructions, price-protection conditions and UTA liquidation process. LTP-based TP/SL can also be delayed by an enabled price-protection threshold. The existing AMR caveat above remains applicable: automatically added funds can increase the position’s total loss exposure beyond its original margin.
39. The Impact of High Leverage on the Liquidation Structure
The higher the leverage, the lower the initial margin required for the position, but the liquidation price tends to be closer to the entry price.
For example, if you increase a position in the same direction by:
- 2x
- 5x
- 10x
- 20x
- 50x
the likelihood of reaching the maintenance margin threshold increases even with a small unfavorable price movement.
In other words, with high leverage, the fact that my position reaches the liquidation price much faster is a more important realistic risk than the Insurance Fund and ADL.
40. Why You Should Not Trade Looking Only at the Liquidation Price
When managing futures positions, you should at least look at the following five items together.
| Item | Meaning |
|---|---|
| Entry Price | Actual entry price |
| Mark Price | Mark price important for liquidation judgment |
| Liquidation Price | Forced liquidation threshold |
| Bankruptcy Price | Settlement threshold where margin becomes zero |
| ADL Indicator | Auto-deleveraging priority in extreme markets |
You must distinguish these five to properly understand the Bybit liquidation screen.
41. Why Do the Liquidation Price and Last Price Move Differently?
Forced liquidation judgment generally does not look only at the last traded price, but is based on the Mark Price.
Therefore, even if the Last Traded Price on the chart does not seem to have reached the liquidation price yet, there may be a situation where the Mark Price reaches the liquidation threshold first.
Because of this, beginners sometimes feel:
“The chart price hasn’t reached it yet, so why was I liquidated?”
You should check the Mark Price on the actual position screen together.
42. Can a Negative Balance Remain After Liquidation?
In Perpetual/Futures liquidation, the Insurance Fund plays the role of absorbing excess contract losses that occur at prices worse than the bankruptcy price.
However, in addition to futures, Bybit has:
- Spot Margin
- Crypto Loan
- UTA Borrowing
- Options
etc., which have different risk and debt structures.
Therefore, just because a negative balance is displayed on your account, you should not automatically judge it as “remaining debt from futures liquidation.”
43. The Insurance Fund and General Deposit Insurance Are Completely Different
You might misunderstand because of the name.
The Bybit Insurance Fund is not a system that:
“Protects your deposits up to a certain amount if the exchange goes bankrupt”
like bank deposit insurance.
It is a derivatives risk management fund that handles excess losses exceeding the bankruptcy price during the futures liquidation process.
Therefore, you should not confuse it with depositor protection or asset custody insurance.
44. Does the Insurance Fund Compensate for My Losses?
You must also be careful with the expression here.
The Insurance Fund is not a fund that returns the normal position losses a user lost due to liquidation.
It is a role to handle excess losses caused by market execution worse than the bankruptcy price after the user has exhausted their initial margin.
Therefore:
“I was liquidated, so I get my margin back from the Insurance Fund.”
is not the structure.
45. Do I Lose Money If ADL Occurs?
Opportunity loss may occur depending on the situation.
For example, if a short position is in large profit and the position is automatically closed due to ADL, you will not be able to earn that additional profit even if the market falls further.
Also, there may be a difference between the ADL settlement price and the current market price. Bybit explains that ADL target positions can be settled based on the bankruptcy price of the liquidated position.
Therefore, it is difficult to view ADL simply as “forced closure without loss.”
46. Is ADL Market Manipulation?
No.
ADL is one of the risk management mechanisms for handling extreme market losses at derivatives exchanges.
Bybit discloses ADL occurrence conditions, ranking calculation methods, and Insurance Fund structure in its official help center.
However, users must understand in advance the contract structure that positions can be automatically reduced in extreme situations, unlike general market trading.
47. Four concepts to distinguish
- Stop-loss: a user-set exit order, whose execution price is not guaranteed in fast markets.
- Liquidation: system action when the account or position fails the applicable maintenance-margin test.
- Bankruptcy price: the liquidation engine’s reference price at which the position’s allocated margin is exhausted.
- ADL: reduction of ranked opposing positions if Bybit’s applicable trigger conditions are met.
These mechanisms have different triggers and outcomes. A stop-loss is not a guarantee against liquidation, and the insurance fund is not personal loss insurance.
48. Practical Checklist to Reduce Liquidation Risk
While you cannot change the liquidation system itself, users can reduce the possibility of liquidation.
Lower Leverage
This is the most direct method.
Reduce Position Size
Positions that are too large relative to the entire account are vulnerable to sudden fluctuations.
Set Stop Loss Price in Advance
You can control losses before the position is handed over to the liquidation system.
Consider Using Isolated Margin
If you want to limit the spread of one position’s loss to the entire account, Isolated Margin has a simpler structure.
Check Mark Price
Do not just look at the Last Price; you must check the mark price used for actual liquidation judgment.
Check ADL Indicator
In extreme markets, also check your ADL priority.
49. Things to Check Before Starting Futures Trading on Bybit
If you are starting Bybit futures trading for the first time, it is better to understand the following structure before “how much leverage to use.”
- Trading fees
- Funding fees
- Liquidation price
- Bankruptcy price
- Margin mode
- Insurance Fund
- ADL
If you do not know this structure, it is easy to underestimate the actual risks that occur with high leverage.
50. Bybit Registration and BYBITDC Referral Code
If you do not have a Bybit account yet, you can check if the referral code was properly applied during the registration step.
Bybit Partner Registration Link
Referral Code
BYBITDC
If the referral code is not automatically entered on the registration screen, you can check the referral code input field and enter BYBITDC yourself.
However, Bybit’s new user events, trading fee benefits, bonuses, and regional promotions may change depending on the timing and account conditions. Therefore, rather than expressing that a specific discount rate or bonus is permanently guaranteed, it is accurate to check the actual benefits displayed on the Bybit screen at the time of registration.
Affiliate Notice: The link above is a partner link. If you sign up or trade through this link, the site operator may receive a certain commission. The actual promotions and discount conditions applied to the user may vary depending on Bybit’s policy at the time.
51. Frequently asked questions
Where does a liquidated position’s remaining margin go?
Bybit says a close better than the bankruptcy price credits the insurance fund; a worse close draws on it for excess contract losses. The difference is not a personal refund.
Can the insurance fund repay my ordinary trading loss?
No. It is a risk pool for excess losses after liquidation, not deposit insurance or compensation for an individual’s normal loss.
Must the insurance fund reach zero before ADL starts?
No. Bybit also specifies a pair-specific eight-hour drawdown trigger. A separate trigger applies when the combined balance of certain independent pools is at or below zero. Check the current pair-level trigger and stop parameters.
Which opposing position can be auto-deleveraged?
Bybit ranks positions by leveraged return; profitable positions have priority, but an opposing losing position is not categorically excluded. The on-screen ADL indicator shows relative priority, not a promise that ADL will happen.
What happens to orders if my position is selected for ADL?
Bybit says affected active orders are canceled and the selected position can be reduced or closed at the applicable bankruptcy price. Check your position and order history and Bybit notifications.
Can a chart candle prove that liquidation did not occur?
Not by itself. Liquidation uses the relevant Mark Price, while the visible candle may show Last Traded Price. The bankruptcy reference is not necessarily a trade print on that candle.
Are the 65,000 and 64,000 USDT prices a current quote?
No. They are Bybit’s illustrative isolated-long example. Actual thresholds, fees and outcomes depend on the contract, margin mode and account conditions.
52. Bybit Liquidation Fund Flow at a Glance
| Step | Occurrence |
|---|---|
| 1 | Position loss increases |
| 2 | Mark Price reaches liquidation threshold |
| 3 | Liquidation engine takes over position |
| 4 | Settlement based on bankruptcy price |
| 5-A | Actual closing price is better than bankruptcy price → Insurance Fund increases |
| 5-B | Actual closing price is worse than bankruptcy price → Insurance Fund bears excess loss |
| 6 | Applicable eight-hour drawdown or combined independent-pool condition met → ADL possible |
53. Most Common Misconceptions
| Common Misconceptions | Actual Structure |
|---|---|
| The exchange takes all margin upon liquidation | The difference between bankruptcy price and execution price is linked to the Insurance Fund system |
| Liquidation price and bankruptcy price are the same | They are distinct concepts |
| The Insurance Fund returns my liquidation losses | A system reserve used to handle excess liquidation losses |
| If the Insurance Fund is large, I will not be liquidated | Independent of an individual user’s liquidation status |
| ADL occurs only to those who are losing money | Can also target opposite profitable/high-leverage positions |
| ADL occurs only when the Insurance Fund reaches exactly zero | Additional ADL trigger conditions exist in 2026 |
| Bybit charges a separate liquidation fee for futures | There is no separate liquidation fee for Perpetual/Futures |
54. Short definitions
For users looking for quick concept definitions, here is a brief summary:
What is Bybit Liquidation?
Bybit liquidation is the process where the liquidation engine forcibly takes over a position and settles it based on the bankruptcy price when the position fails to meet the maintenance margin requirements.
What is the Bybit Bankruptcy Price?
The bankruptcy price is the price at which the position’s margin balance reaches zero.
What is the Bybit Insurance Fund?
The Insurance Fund is a risk reserve designed to absorb excess losses that occur when a liquidated position is closed at a price worse than the bankruptcy price.
What is Bybit ADL?
ADL (Auto-Deleveraging) can reduce high-ranked opposing positions when an applicable Bybit trigger is met; the current eight-hour drawdown and combined independent-pool conditions are described in the official ADL rules.
55. Final Summary
It is inaccurate to understand that when a futures position is liquidated on Bybit, “the exchange simply took my money.”
The actual structure is much more systematic.
Liquidation price reached → Liquidation engine takeover → Settlement based on bankruptcy price → Excess loss between actual closing price and bankruptcy price covered by the Insurance Fund → ADL possible only if an applicable published trigger condition is met
In particular, you must remember the following:
- Liquidation price and bankruptcy price are different.
- The bankruptcy price is the level where the margin becomes zero.
- If a liquidated position is closed at a price better than the bankruptcy price, the Insurance Fund may increase.
- If it is closed at a price worse than the bankruptcy price, the Insurance Fund covers the excess loss.
- ADL may occur if the published pair-specific drawdown or combined independent-pool condition is met.
- ADL can occur not only to users who are losing money but also to opposite profitable/high-leverage positions.
- Bybit ADL in 2026 cannot be explained solely by whether the Insurance Fund balance is zero.
- Bybit states that it does not charge a separate liquidation fee for Perpetual/Futures.
The most important thing in futures trading is not where the money goes after liquidation, but managing risk before your position is handed over to the liquidation engine.
It is more important to lower leverage, limit position size, check both the Mark Price and liquidation price, and, if necessary, set a stop-loss well before the liquidation price.
Referral-code eligibility is separate from liquidation mechanics. Any applicable terms must be checked in the account and official rules; no code changes margin or removes liquidation and ADL risk.
Bybit Partner Link:
https://partner.bybit.com/b/BYBITDC
Referral Code:BYBITDC
Registration benefits and promotions may change depending on country, timing, and account conditions, so it is accurate to verify based on the conditions displayed on the actual registration screen.
Disclaimer: This content is for informational purposes to explain Bybit futures liquidation, bankruptcy price, Insurance Fund, and ADL structure, and does not constitute investment advice. Cryptocurrency derivatives and leveraged trading carry the risk of total loss of principal and forced liquidation. Bybit’s liquidation, Insurance Fund, and ADL policies are subject to change, so you should check the latest official help articles and the trading interface before actual trading.
Official sources and scope of examples
Checked October 23, 2026: the notes and diagrams below. This is a document review, not an actual transaction test. Examples use stated assumptions.
ADL is not limited to a fund balance reaching zero. Current rules include an eight-hour drawdown trigger and a separate combined independent-pool balance condition. Use the trading pair’s current parameters; do not treat the 30%/25% example as universal. The insurance fund is not deposit insurance.