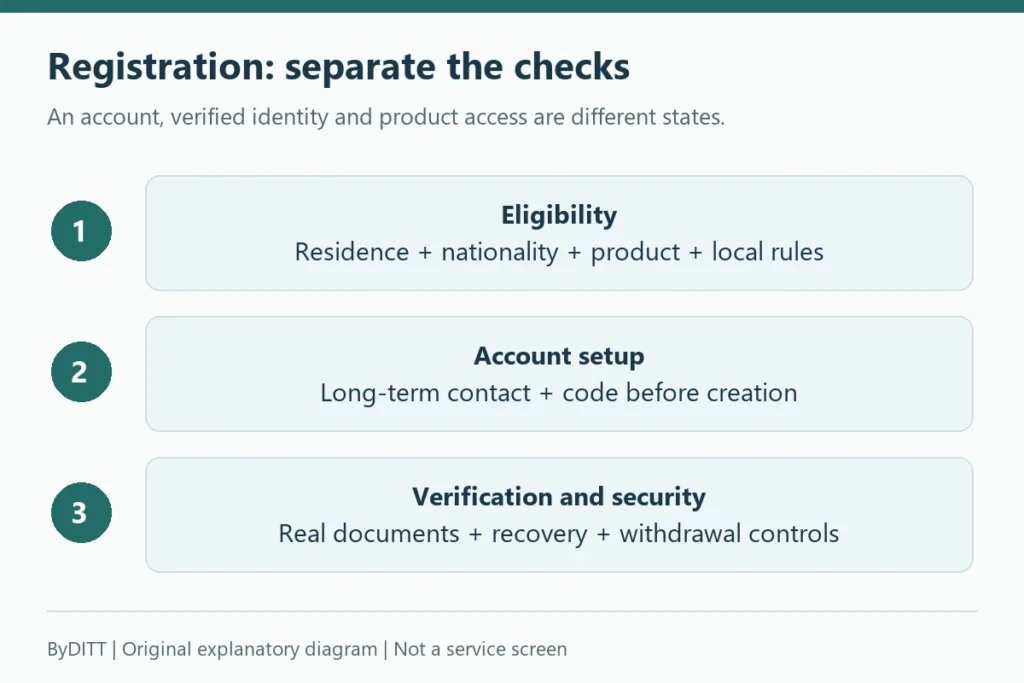
Bybit Card fees depend on the card program, payment currency and whether fiat or crypto funds the transaction. Check eligibility using your actual country of residence before comparing costs; an exchange account or a regional fee table does not establish card eligibility. This guide separates foreign exchange, crypto conversion and ATM charges so you can reconcile a quoted purchase with the amount actually deducted.
Official information checked: 12 October 2026. Regional terms and account settings can change. The examples below are independent ByDITT calculations, not live quotes or a recommendation to apply.
Bybit Card eligibility: which country and program apply?
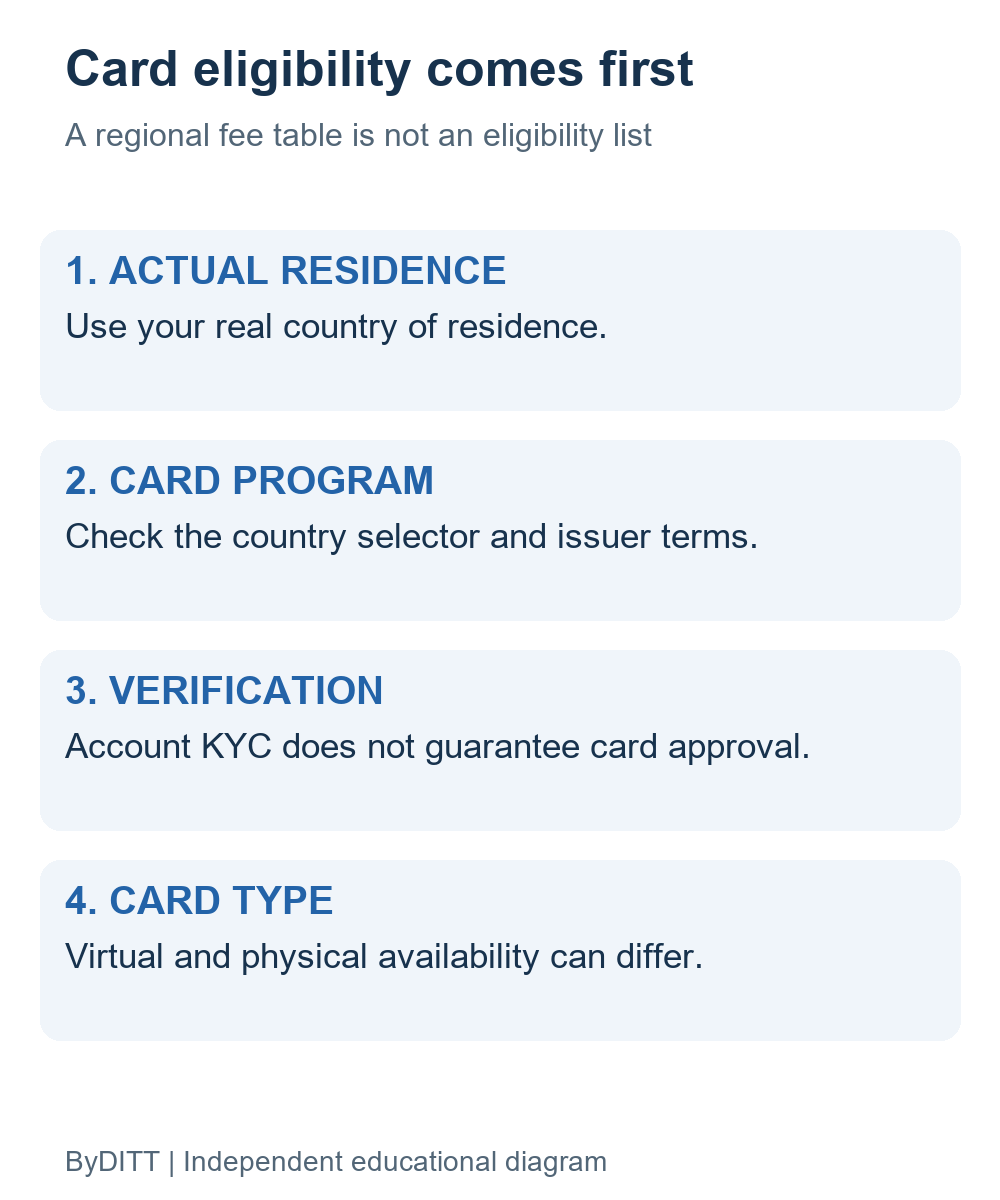
Start with Finance → Card → Country of Residence in the official application flow. Enter your real residence, then review the program, verification requirements and cardholder terms offered to that account. Bybit says card access is limited to supported countries, and card identity checks can require updates even when exchange-account KYC is complete. A physical card requires an approved virtual card and is rolled out separately. See the official application guide.
For Korean-language readers: this article does not confirm that a South Korean resident can obtain a Bybit Card. “Asia Pacific” is a program label, not evidence that every country in Asia qualifies. Language, nationality, current travel location and verified residence are different facts. Do not select another country or use an inaccurate address to get past an eligibility check.
The EEA and Switzerland also require particular care: Bybit’s EEA/CH service-change FAQ discusses migration and the separate Bybit EU service. Do not carry a bybit.com fee or eligibility assumption into a bybit.eu card application. Check the legal entity and current program terms first.
What funds a Bybit Card payment?
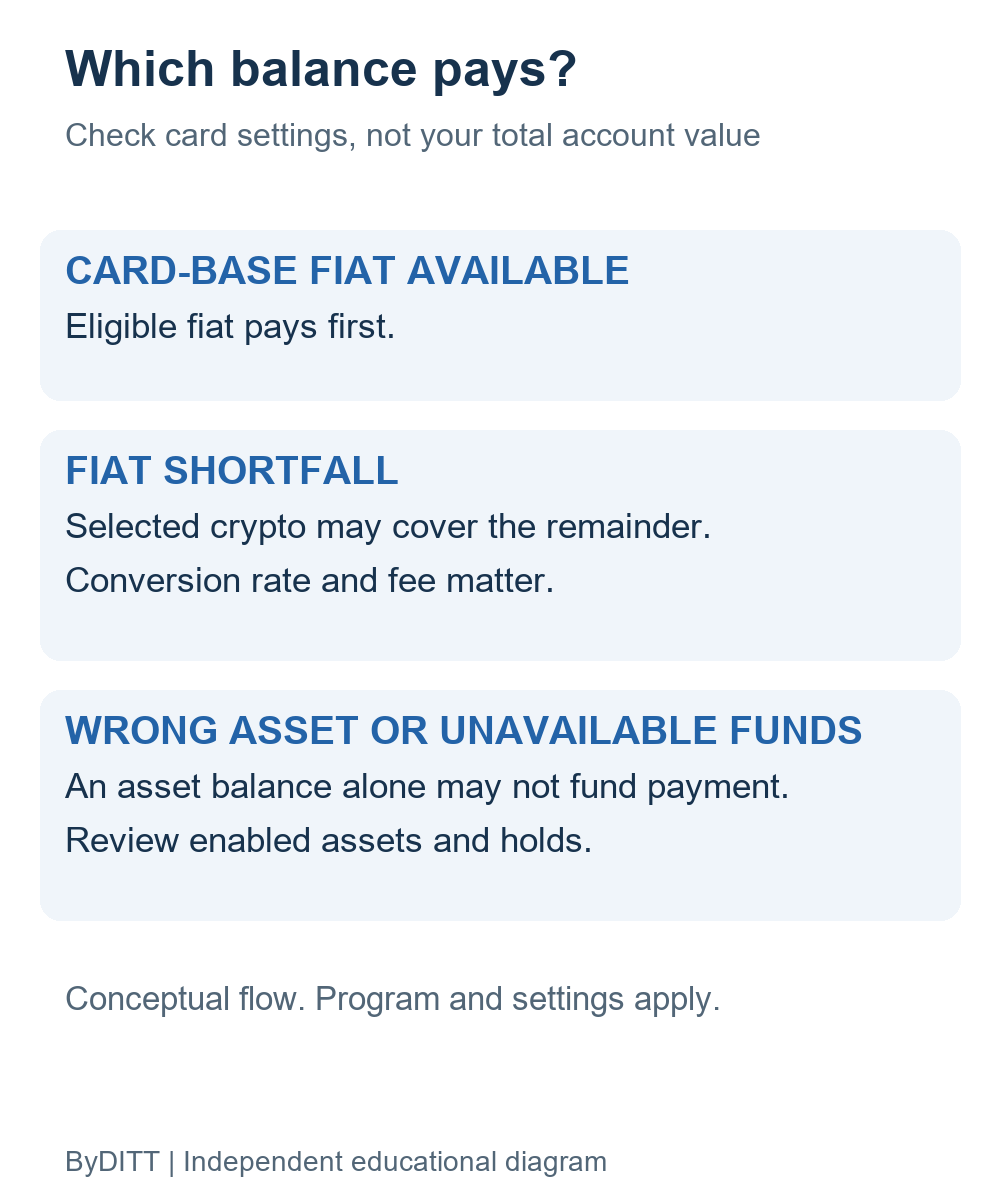
Bybit’s transaction guide describes eligible card-base fiat being used first; a shortfall can be covered by selected crypto at the One-Click Sell rate plus a conversion fee. Its example also shows why a balance in a different fiat currency is not necessarily spendable by that card. Crypto that exists in your account but is not selected for payment can likewise leave a transaction unfunded.
Check the actual “Paying With” configuration rather than adding together every asset shown on the exchange. The general card FAQ describes Funding Account and Flexible Easy Earn balances as funding sources and lets users manage supported crypto priority. Available sources and settings should be confirmed for your program; this is not a promise that every Earn product or every coin can pay.
For a practical reconciliation, record four things before a payment: the card’s base currency, the eligible fiat available, the enabled crypto order and any reserved balance. After settlement, compare those records with the final debit. This makes a conversion explainable without treating a temporary hold or unrelated account asset as a fee.
Moving assets into an account is a separate operation from paying by card. For network compatibility and the amount received after transfer fees, see ByDITT’s Bybit deposits and withdrawals guide.
Regional Bybit Card fees: compare the right cost layer
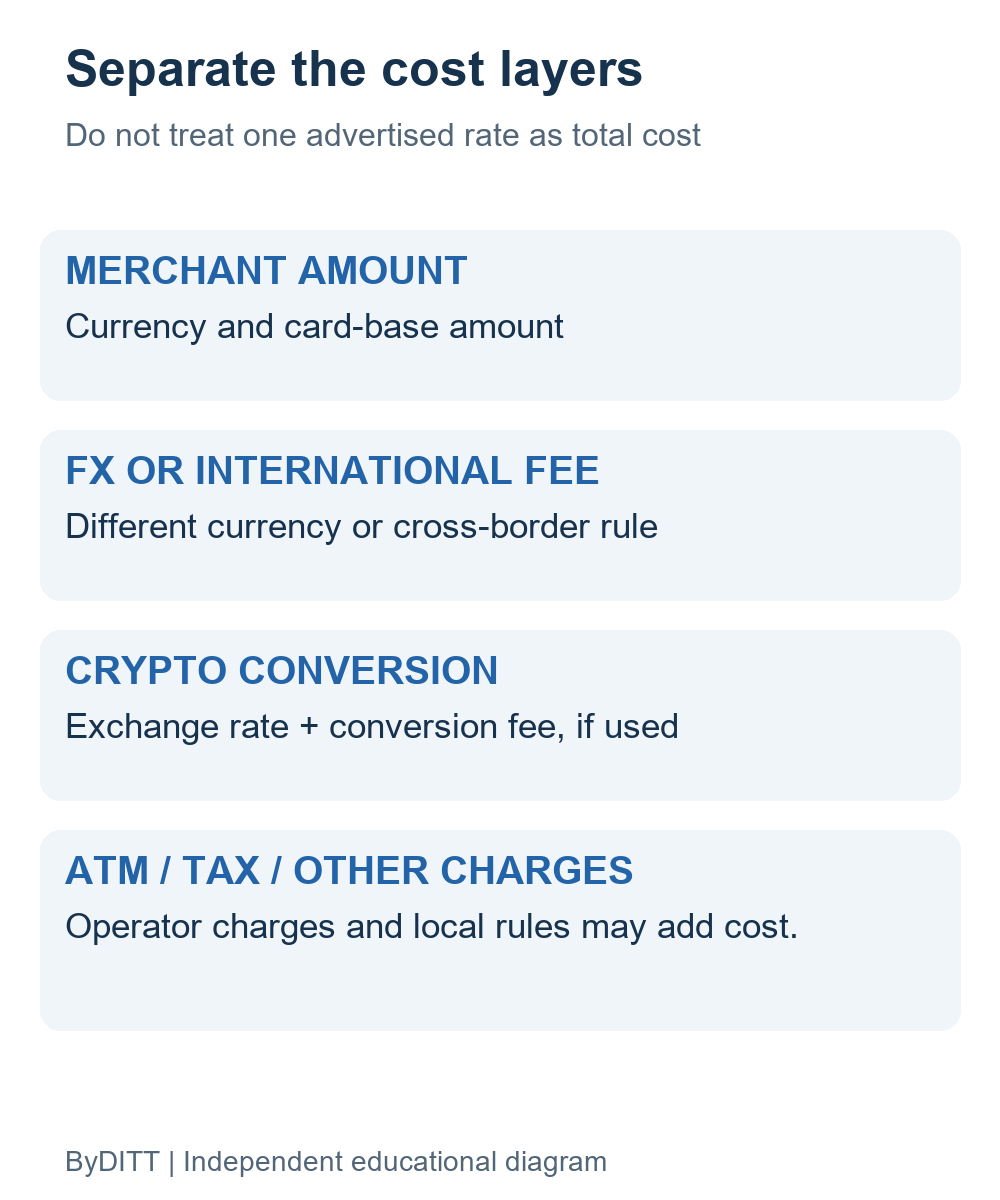
The following selected rates come from the official Fees and Limits schedule, whose displayed update date was 10 September 2026 when checked. FX percentages are additional to the network exchange rate; crypto conversion percentages are additional to the One-Click Sell rate. These are not interchangeable exchange rates.
| Card program | FX / international | Crypto conversion |
|---|---|---|
| Australia / Asia Pacific / Georgia | 2% FX | 0.9% |
| Kazakhstan (AIFC) | 2% international | 0.9% |
| Argentina | 7% FX | 0.5% |
| Brazil | 1.5% FX | 0.9% |
| Mexico | 2% FX | 0.9% |
Ordinary FX is triggered by a currency different from the card denomination. Kazakhstan (AIFC) instead has an international charge on cross-border purchases, including USD purchases outside Kazakhstan. The distinction matters: “paid in USD” does not by itself mean “no international fee.”
This is a selected comparison, not a complete issuance, tax or limit schedule. Peru, virtual-versus-physical availability, replacement costs and account-specific limits need their own current checks. A free virtual-card issuance does not mean free foreign spending or free crypto conversion. Keep acquisition cost, ongoing payment cost and possible taxes in separate lines of your comparison.
A 100 USD purchase: four independent budgeting examples
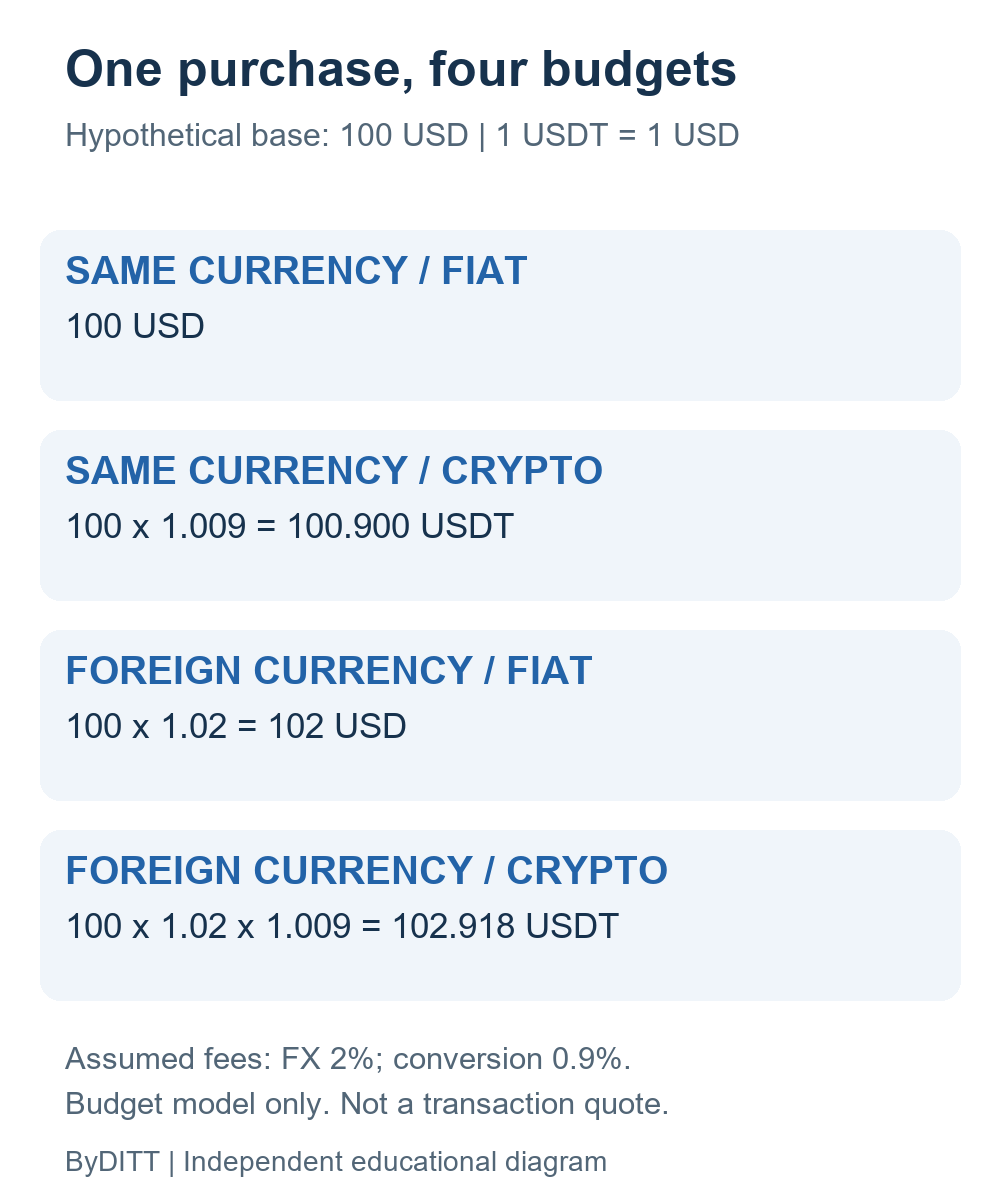
The following is a simplified budgeting model, not Bybit’s settlement quote. Assume the merchant amount has a card-base value of 100 USD, an applicable FX charge of 2%, crypto conversion of 0.9%, and an assumed conversion rate of 1 USDT = 1 USD. For the combined case, assume conversion funds the full amount including FX. Ignore taxes, operator charges, rounding, rate movement and minimum-conversion effects. Each row is a separate purchase, not a sequence of payments.
| Scenario | Calculation | Model debit |
|---|---|---|
| Same currency, fiat | 100 | 100 USD |
| Same currency, crypto | 100 × 1.009 | 100.900 USDT |
| Foreign currency, fiat | 100 × 1.02 | 102 USD |
| Foreign currency, crypto | 100 × 1.02 × 1.009 | 102.918 USDT |
The last row is deliberately a conditional model. It is not a claim that the platform always applies fees in that sequence or that USDT always equals USD. It shows why simply adding 2% and 0.9% can miss a charge applied to an already-increased amount. If only part of a purchase needs crypto, apply your budgeting assumption only to that part, then compare it with the actual transaction record.
For your own comparison, replace every assumption: merchant currency and amount, network-converted base amount, program fee, fiat contribution and actual crypto quote. A lower listed conversion percentage can still produce a worse total if the exchange rate differs. Compare the same purchase and timing, not two unrelated advertised percentages.
ATM fees, allowance and operator conversion are different checks
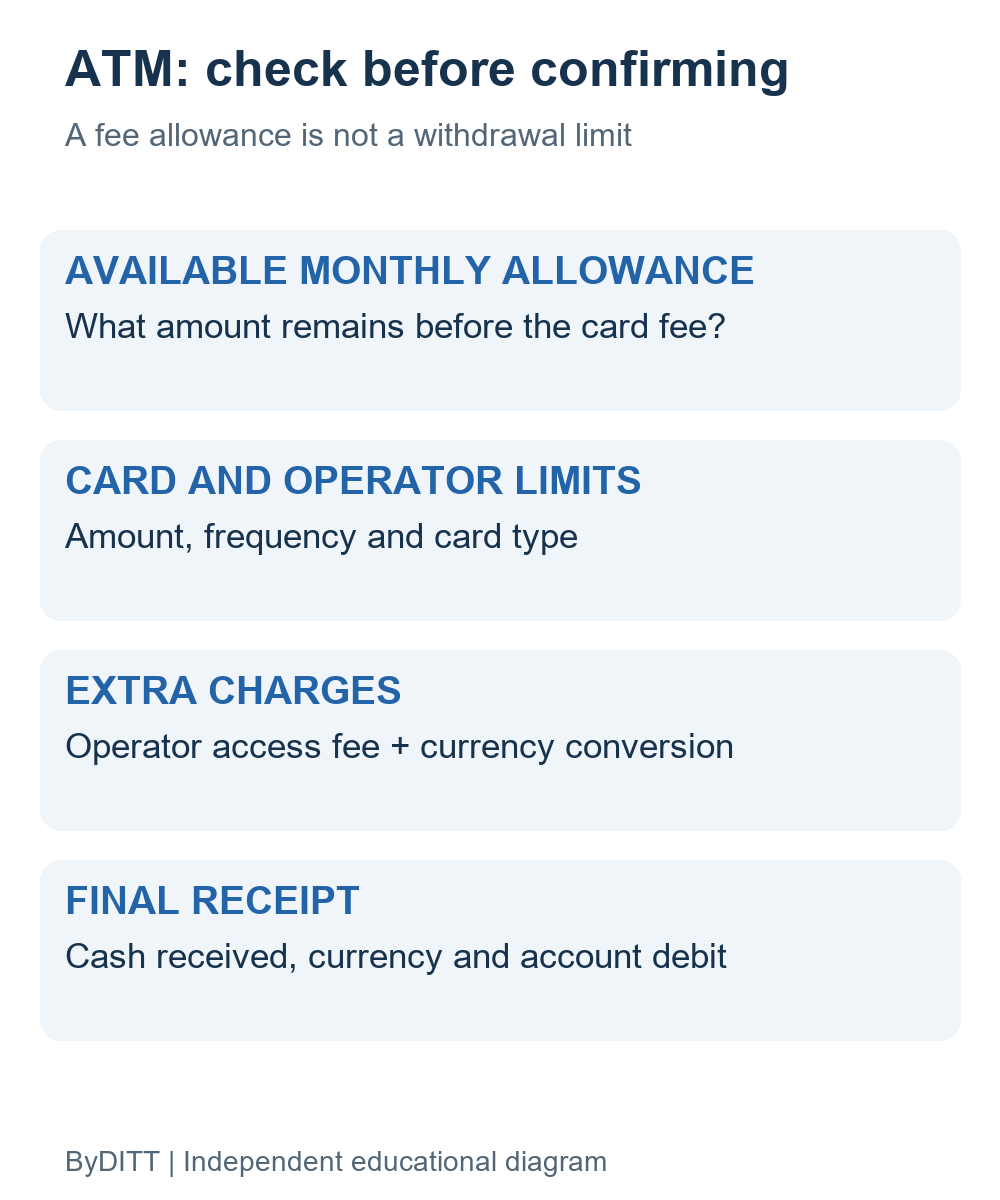
A monthly card-fee allowance is not the maximum cash you can withdraw. The card FAQ distinguishes card fees and possible FX/crypto costs from ATM-operator access fees or conversion offers. Virtual-card withdrawal also depends on the ATM and local network; contactless capability alone is not a guarantee.
Before confirming, compare the remaining monthly allowance with the requested amount, then inspect both the card’s withdrawal limits and the operator’s limit. Read the ATM’s own access charge and conversion quote. If it offers conversion into your card currency, identify who is providing that rate; do not assume it is the same as the card-network conversion. Cancel an unclear quote before confirmation rather than trying to infer the cost afterward.
Independent allowance example: assume a program charges 2% only on withdrawals exceeding a 100 USD monthly allowance. If earlier withdrawals used 80 USD and the next withdrawal is 50 USD, 20 USD remains within the allowance and 30 USD is above it. The modeled card ATM fee is 30 × 2% = 0.60 USD, before any operator, FX, conversion or tax cost. Replace the allowance and rate with your actual regional schedule. Do not apply this hypothetical USD threshold to every country.
Why the held amount and final debit can differ
Authorization reserves funds before the merchant completes the transaction. The transaction guide distinguishes that reservation from final deduction. The fee schedule also describes FX padding as an authorization buffer for exchange-rate changes; excess reserved funds are released. A higher pending amount therefore needs investigation, but is not automatically a permanent fee.
Keep the receipt, merchant currency, transaction identifier, authorization date, pending amount and settled amount. When asking official support about a discrepancy, describe the status and the specific difference. Never send a PIN, CVV, login password or authentication code to someone claiming they can release a hold.
Checks before relying on the card
- Eligibility: real residence, supported program, identity/address checks and current issuer terms.
- Funding: card-base fiat, selected crypto, available source and balances reserved elsewhere.
- Cost: actual exchange rates, FX or international fee, conversion, ATM charges and applicable taxes.
- Availability: virtual/physical status, merchant acceptance, limits and an alternative payment method.
- Evidence: save the fee schedule date and compare the settled debit with the original receipt.
Frequently asked questions
Does a Bybit account or completed KYC guarantee card eligibility?
No. The card application has its own residence, verification and program checks. Use the country selector and current terms; this guide does not confirm South Korean resident eligibility.
Is Bybit Card the same as buying crypto with a bank card?
No. This article is about spending through a Bybit-issued card program. A bank-card purchase of crypto is a different transaction with its own provider, payment and account conditions. Do not transfer one product’s fee to the other.
Does BYBITDC reduce card FX or ATM fees?
No card-fee reduction is established by this article. BYBITDC is an affiliate referral code, not evidence of a different card tariff. The Bybit referral registration page with BYBITDC can be consulted to inspect any displayed account-registration terms. Verify any offer separately; do not assume it changes card eligibility, exchange rates, FX or ATM charges.
Should a pending extra amount be added to my final cost?
Not automatically. Separate authorization from settlement, then reconcile any released reserve and the actual debit. Escalate an unexplained settled difference through official support.
Sources, verification and editorial limits
Official pages reviewed on 12 October 2026: Fees and Limits (displayed update 10 September 2026); How to Get Started (10 June 2026); How Transactions Work (5 October 2026); General Inquiries FAQ (3 September 2026); and EEA/CH service-change FAQ (10 June 2026). An update date is not a guarantee that every country or account has identical current terms.
Independent-site and affiliate disclosure: ByDITT is an independent educational and affiliate site, not Bybit.com or a card issuer. ByDITT may receive compensation through the referral link. That creates an economic conflict of interest; no reward, fee reduction, approval or suitability is guaranteed.
Risk notice: Crypto prices and conversion rates can change, custodial funds may become inaccessible, cards or accounts may be restricted, and regulation and tax treatment vary. Spending crypto can have tax consequences depending on jurisdiction; this guide is not tax, legal or investment advice. Card spending is distinct from derivatives trading: using margin or leveraged products elsewhere creates separate liquidation and loss risks. Keep payment needs separate from trading collateral and confirm account-specific conditions with the official provider.